Stand-Up India Scheme Extended to 2031: Eligibility and Loan Rules
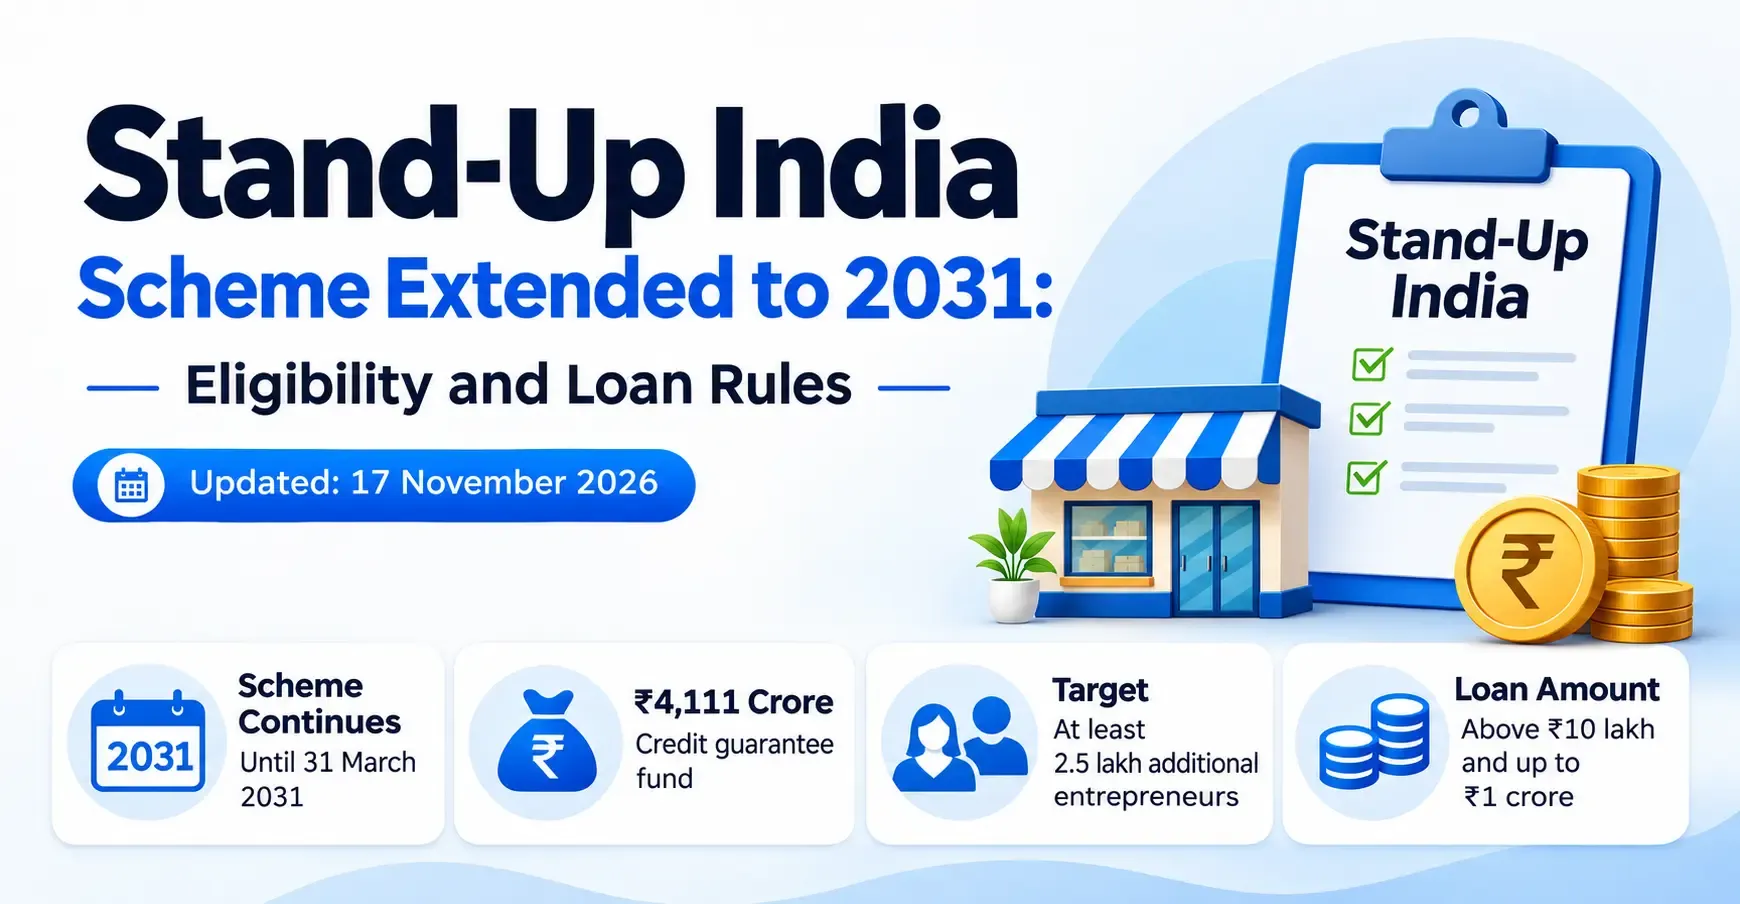
- The Stand-Up India Scheme will continue until 31 March 2031.
- The government has approved a ₹4,111 crore credit guarantee fund.
- The scheme targets at least 2.5 lakh additional women and SC/ST entrepreneurs.
- Loans are available above ₹10 lakh and up to ₹1 crore for new businesses.
Starting a new business can require more money than an entrepreneur can provide on their own. Stand-Up India helps eligible women and Scheduled Castes/Scheduled Tribes (SC/ST) entrepreneurs obtain a bank loan to start a new venture. This guide covers what the 2026 extension means, who can apply, how the loan works, and where to submit an application.
Give Your New Business a Strong Start with BUSY
Starting a new business? Use BUSY to manage invoices, expenses and accounts from day one.
- Professional GST Billing
- Inventory Management
- Business Reports
What changed in the 2026 Stand-Up India announcement?
On 11 November 2026, the Union Cabinet approved the continuation of the scheme until 31 March 2031. The Cabinet announcement, published as PIB Release ID 2334978, approved a ₹4,111 crore credit guarantee fund and set a target of supporting at least 2.5 lakh additional entrepreneurs.
The guarantee will cover 85% of the loan amount, with a standard guarantee fee of 0.50%. This protection is provided to lenders. It does not cancel the borrower’s repayment responsibility or guarantee approval.
Stand-Up India loan eligibility
The scheme is available to women and SC/ST entrepreneurs aged at least 18 who plan to establish a greenfield enterprise. A greenfield enterprise is a completely new business venture. The main conditions are:
- The proposed business must be in manufacturing, services, trading, or an activity connected with agriculture.
- A company or partnership must be at least 51% owned and controlled by eligible women or SC/ST entrepreneurs.
- The applicant must not have defaulted on a loan from a bank or financial institution.
- The borrower must contribute at least 10% of the project cost.
The lender makes the final decision after reviewing the project and the applicant’s ability to repay.
How Stand-Up India can fund a new business
How much funding is available?
The Stand-Up India loan amount must be above ₹10 lakh and can go up to ₹1 crore. The loan may cover up to 85% of the project cost. It can be issued as a term loan or a composite loan. A term loan is usually used to cover setup costs or business assets. A composite loan combines that longer-term funding with working capital for regular operating expenses.
How to apply
Applicants can approach a participating Scheduled Commercial Bank. The Department of Financial Services also lists Stand-Up Mitra and JanSamarth as application and guidance routes.
Prepare a project report explaining the business, funding requirement, and expected income. The lender will provide the final document checklist.
Conclusion
The continuation of the Stand-Up India Scheme gives eligible women and SC/ST entrepreneurs more time to seek bank finance for a new venture. Before applying, confirm that the proposed business meets the scheme’s greenfield requirement and that you can provide the required contribution.
A clear project report will help the bank assess whether the business can support the requested loan and repayment schedule.