MUDRA Loan Update 2026: Guarantee Fund Continued Until 2031
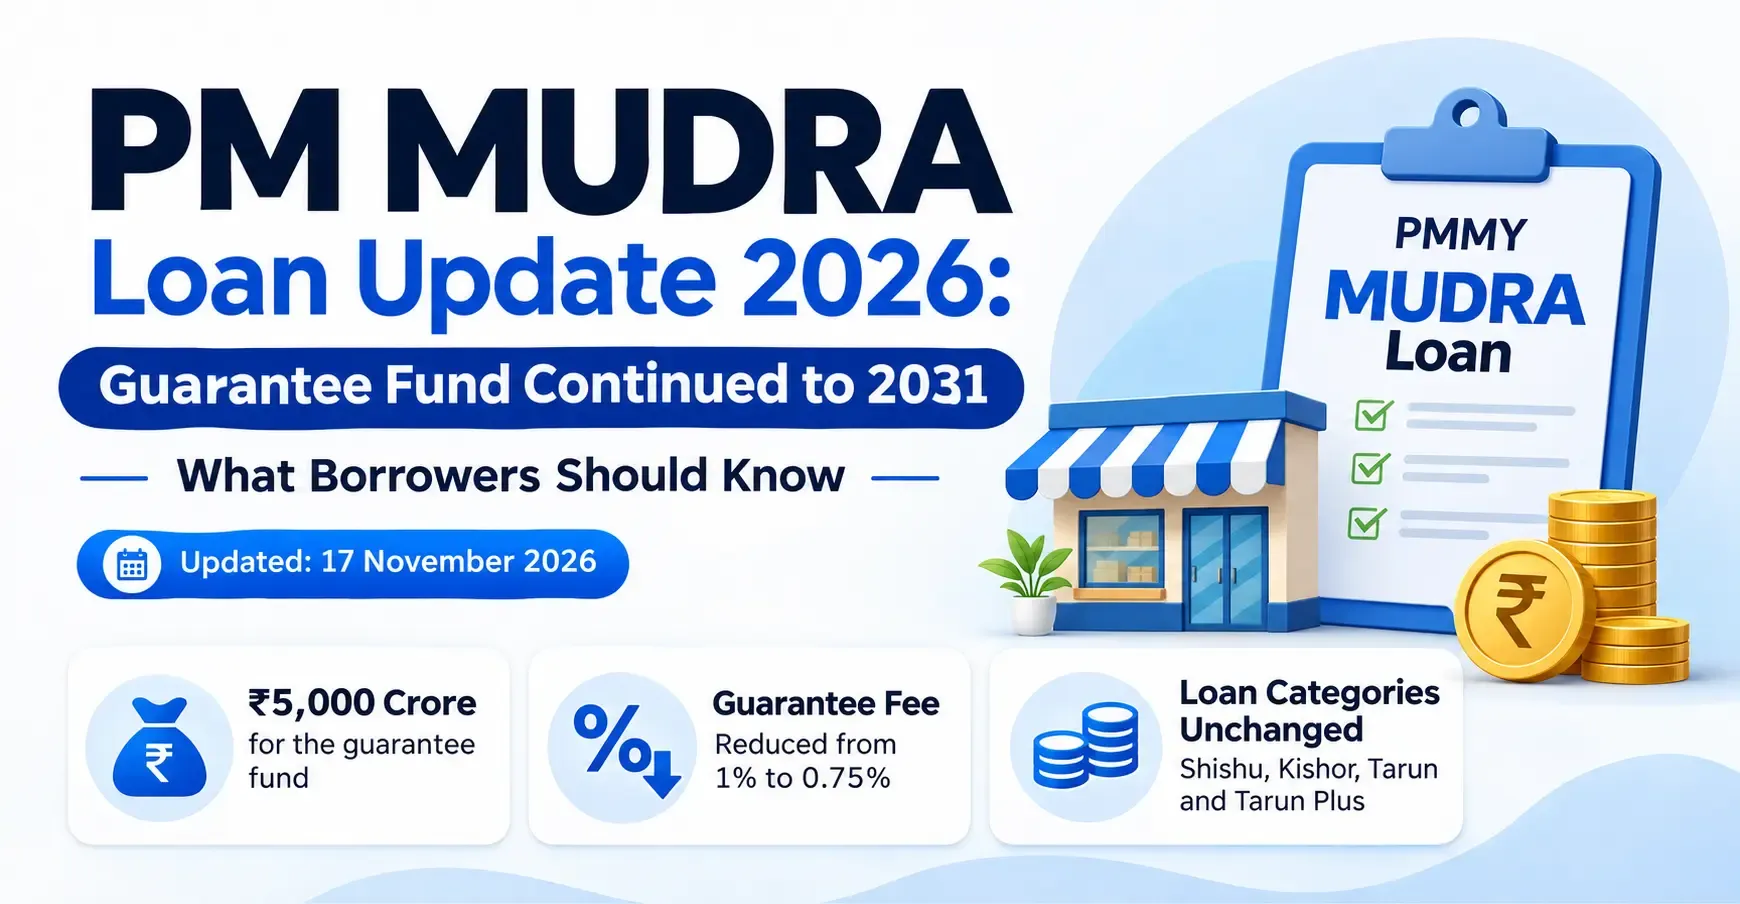
- The Credit Guarantee Fund for Micro Units, which supports eligible MUDRA loans, will continue until 31 March 2031.
- The government has approved ₹5,000 crore for the fund. It expects this to support ₹12.6 lakh crore in PMMY lending over five years.
- The annual guarantee fee paid under CGFMU has been reduced from 1% to 0.75%. This does not automatically reduce a borrower’s interest rate.
- MUDRA loan categories remain unchanged. Tarun Plus is available only to borrowers who have successfully repaid a Tarun loan
MUDRA loans are designed to help micro-enterprises obtain business credit without pledging collateral. These loans are supported by the Credit Guarantee Fund for Micro Units, or CGFMU, which reduces the risk taken by participating lenders.
On 11 November 2026, the Union Cabinet approved the fund’s continuation until 31 March 2031. For business owners, the important question is how this decision affects MUDRA applications and borrowing.
Applying for a MUDRA loan?
Keep your finances organised and business records ready with BUSY.
- Sales & Expense Tracking
- Financial Reports
- Receivables & Payables Management
What changed in the 2026 MUDRA announcement?
The Pradhan Mantri MUDRA Yojana, or PMMY, provides business loans through banks and other approved lenders. The Credit Guarantee Fund for Micro Units, or CGFMU, protects lenders against a portion of the loss if an eligible loan is not repaid.
The Cabinet approval published as PIB Release ID 2334976 provides ₹5,000 crore for CGFMU. The fund is expected to support ₹12.6 lakh crore in PMMY lending from FY 2026-27 to FY 2030-31. Its annual guarantee fee has been reduced from 1% to 0.75%.
Was the MUDRA scheme extended until 2031?
The Cabinet decision continued CGFMU rather than launching a new version of PMMY. The fund applies to eligible PMMY loans issued from FY 2026-27 to FY 2030-31. It did not create new eligibility rules or loan categories. The application process also remains unchanged.
MUDRA eligibility, loan limits and application
MUDRA loan categories and limits
For Mudra Loan eligibility, the applicant must seek funding for an income-generating business activity and have a workable business plan. Eligible fields include manufacturing, trading, services and activities connected with agriculture.
Applications are handled by participating banks, non-banking financial companies (NBFCs), and microfinance institutions. The lender checks whether the business meets the scheme rules and can repay the requested amount. The Mudra Loan limit shown for each category is the maximum available, not a guaranteed loan amount.
| Category | Loan amount | Who it is for |
|---|---|---|
| Shishu | Up to ₹50,000 | The smallest business funding needs |
| Kishor | Above ₹50,000 and up to ₹5 lakh | New or operating small businesses |
| Tarun | Above ₹5 lakh and up to ₹10 lakh | Businesses with larger funding needs |
| Tarun Plus | Above ₹10 lakh and up to ₹20 lakh | Only for borrowers who successfully repaid a Tarun loan |
Category
Loan amount
Who it is for
Category
Loan amount
Who it is for
Category
Loan amount
Who it is for
Category
Loan amount
Who it is for
How to apply for a MUDRA loan
First, work out how much the business needs and select the matching loan category. You can then apply through JanSamarth or contact a participating lender.
The lender will provide a document checklist. Keep proof of identity ready, along with records showing the business's performance and how the loan will be used. Processing times differ by lender.
MUDRA loan collateral, interest rates and repayment costs
PMMY provides collateral-free business credit. Collateral is an asset, such as property, that a lender can claim if a loan is not repaid. Collateral-free does not mean approval is automatic. The lender still checks whether the business can repay the loan.
There is no single PMMY interest rate. Each lender sets its rate within applicable Reserve Bank of India rules. The lower CGFMU guarantee fee does not require lenders to reduce borrower interest rates.
What to check before accepting a MUDRA loan
| Check with the lender | Why it matters |
|---|---|
| What is the total amount you will repay? | The interest rate alone does not show the complete cost |
| How much is each payment and when is it due? | The schedule must fit the business’s cash flow |
| Are there any additional charges? | Processing, late-payment or early-repayment fees can increase the cost |
| When and how will the money be released? | Some loans are paid in stages or directly to a supplier |
| What happens if a payment is late? | The approval letter should explain penalties and other consequences |
Check with the lender
Why it matters
Check with the lender
Why it matters
Check with the lender
Why it matters
Check with the lender
Why it matters
Check with the lender
Why it matters
Conclusion
The 2026 Cabinet decision keeps CGFMU support for eligible MUDRA lending in place until 31 March 2031. The update strengthens the lending system rather than changing the loan itself. Applicants should choose the category that matches their funding need and keep their business records ready. Before accepting an offer, make sure the repayment amount fits the business’s cash flow.